Securing a driver’s license represents an important milestone, offering newfound independence and mobility. However, for new drivers in the United States—whether they are teenagers getting behind the wheel for the first time or adults acquiring their initial license—that independence comes with significant financial and legal responsibilities. Among the most critical obligations is obtaining adequate car insurance. In nearly every US state, carrying auto insurance is not merely a recommendation; it is mandated by law to ensure that motorists can cover damages or injuries caused during an accident.
For beginners, navigating the auto insurance landscape can feel overwhelming. The industry uses specialized jargon, complex underwriting algorithms, and wide-ranging premium estimates that vary significantly between providers. New motorists face statistical headwinds: insurance carriers classify inexperienced drivers as higher risk because historical data links lower driving experience with a higher probability of traffic violations and collision claims. Consequently, premium quotes for newly licensed motorists are often substantially higher than the national average.
Understanding the components that determine policy pricing is essential to managing these expenses. Insurance is not a one-size-fits-all product; it consists of multiple modular coverages designed to safeguard different aspects of personal liability, vehicle repair costs, and medical expenditures. Failing to secure the right balance leaves drivers vulnerable either to excessive out-of-pocket expenses following a crash or to overpaying for unnecessary add-ons.
By familiarizing yourself with standard underwriting considerations, legal minimum requirements, and optional protections, you can approach the purchasing process with confidence. Taking control of your policy early helps establish a clean driving history, protect your financial standing, and ensure you remain compliant with state regulations from your very first drive.
Understanding Car Insurance Costs for New Drivers
The cost of car insurance for newly licensed operators in the United States reflects an assessment of actuarial risk. Because underwriters lack an established historical record of driving performance for a beginner, they base their rates on demographic trends, vehicle characteristics, and location-based data. On average, a 16-to-19-year-old driver purchasing an individual policy can face annual premiums exceeding $4,000 to $6,000, depending on the state and carrier, whereas an adult new driver in their late twenties or thirties may experience comparatively lower, though still elevated, rates.
Several core variables dictate the final rate calculated by an insurer:
Age and Driving Experience: Young motorists between the ages of 16 and 24 statistically account for a disproportionate volume of collisions and fatal crashes, largely due to developing hazard recognition and risk assessment skills. As a driver matures and logs violation-free years, rates typically decrease.
Geographic Location: Rates vary considerably by ZIP code. Urban settings with dense traffic congestion, elevated rates of vehicle theft, and higher litigation frequencies yield steeper premiums than quiet suburban or rural areas. State-level regulatory structures and mandatory minimum limits also establish different pricing baselines.
Vehicle Type and Safety Ratings: The car being insured directly affects rate structures. High-horsepower sports cars, luxury vehicles with expensive parts, and models with poor crash ratings command high rates. Conversely, midsize sedans and crossover SUVs equipped with modern driver-assist suites and strong crash-test records reduce potential claim payouts.
Credit-Based Insurance Scores: In most US states (excluding California, Hawaii, Massachusetts, and Michigan, where the practice is restricted or banned by state law), insurers evaluate credit-based insurance scores. Statistical correlations indicate that drivers who manage credit reliably tend to file fewer insurance claims.
Recognizing these cost drivers allows new motorists to plan and avoid common financial pitfalls when selecting a vehicle and policy structure.
Essential Coverage Options Every New Driver Needs
When assembling an auto insurance policy, drivers must choose between mandatory baseline requirements and comprehensive protective layers. Relying solely on the bare minimum required by state law frequently leaves substantial coverage gaps. A well-rounded policy typically includes a mix of the following standard components:
Bodily Injury and Property Damage Liability: Liability coverage is compulsory across almost all states. It pays for third-party medical treatments, rehabilitation, lost wages, and property damage resulting from an accident where the policyholder is legally at fault. State minimum limits—often expressed as split limits such as 25/50/25 ($25,000 bodily injury per person, $50,000 per accident, and $25,000 property damage)—are rarely sufficient to satisfy the damages of a severe multi-car collision. Industry professionals often recommend higher baseline limits, such as 100/300/100, to shield personal savings.
Collision Coverage: This optional coverage reimburses the policyholder for structural damage to their own automobile resulting from an impact with another vehicle, a tree, a guardrail, or a rollover event, regardless of fault. If a vehicle is financed or leased, lienholders universally mandate collision coverage until the balance is paid.
Comprehensive Coverage: Comprehensive coverage addresses physical damage arising from incidents outside the driver’s operational control. This includes theft, vandalism, windshield breakage, fire, hail, fallen branches, and collisions with animals. Like collision coverage, comprehensive protection requires a deductible payment before reimbursement begins.
Personal Injury Protection (PIP) and Medical Payments (MedPay): Mandatory in “no-fault” states and available in many others, PIP covers medical costs, lost income, and essential service expenses for the driver and passengers regardless of who caused the incident. MedPay functions similarly but focuses strictly on direct healthcare bills without covering wage losses.
Uninsured/Underinsured Motorist Protection (UM/UIM): Despite legal mandates, millions of motorists drive without insurance or carry limits too low to cover catastrophic injuries. UM/UIM steps in to cover your medical care and vehicle repairs if you are struck by a hit-and-run motorist or an at-fault driver lacking adequate policy limits.
Proven Ways to Lower Your Premiums and Save
While new motorists encounter higher baseline rates, several practical strategies exist to mitigate these costs and make coverage substantially more affordable:
Remain on a Family or Multi-Car Policy: For teenagers and young adults residing with parents or guardians, joining an existing household policy is almost always more cost-effective than taking out an individual policy. Multi-car and multi-driver discounts provide economies of scale, often saving families up to 25% to 35% compared to purchasing separate coverage.
Capitalize on Good Student and Academic Discounts: Many major national insurers offer premium reductions—frequently ranging from 10% to 20%—for high school and college students who maintain an unweighted 3.0 GPA (“B” average) or higher, appear on the Dean’s List, or score in the upper percentiles on standardized tests.
Complete Approved Defensive Driving Courses: Enrolling in state-accredited driver training programs or defensive driving curricula can qualify a motorist for insurer discounts. Beyond financial savings, these programs reinforce safe operational habits that reduce accident likelihood.
Opt for Usage-Based or Telematics Programs: Most prominent carriers now feature opt-in telematics programs tracked via smartphone applications or plug-in onboard diagnostic (OBD-II) units. These programs track metrics such as speed, hard braking, rapid acceleration, mileage, and time of day driven. Careful drivers can earn immediate participation discounts followed by performance-based renewals.
Calibrate Your Deductible Strategically: Raising comprehensive and collision deductibles from $500 to $1,000 lowers ongoing monthly premiums. However, drivers must ensure they have that deductible amount liquid in emergency savings should a repair claim arise.
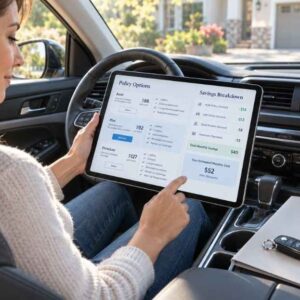
Compare Quotes Systematically: Auto insurance rates differ significantly from one carrier to the next for identical profiles. Requesting comparative quotes from at least three to five independent, direct, or regional providers ensures you identify competitive pricing.
Making an Informed Decision: Securing Long-Term Protection
Selecting an insurance policy marks the beginning of a long-term financial relationship that evolves alongside your driving experience. The primary objective when establishing your initial coverage is not solely securing the lowest conceivable monthly payment, but ensuring your liability limits adequately protect your assets and future earnings. Underinsuring to save nominal amounts each month introduces substantial exposure to personal lawsuits and out-of-pocket loss in the event of an unexpected collision.
As a newly licensed driver, your initial rates will not remain permanently elevated. Insurance carriers continuously evaluate your risk profile over time. By maintaining a clean driving record—free of speeding citations, reckless driving violations, and at-fault collisions—your risk tier improves steadily. Most motorists observe noticeable rate reductions after reaching age 21, and further adjustments after age 25, provided their driving records remain unblemished.
It is advisable to treat auto insurance as an active portfolio rather than a static expense. Plan to review your policy terms and solicit updated quotes annually or whenever major life milestones occur, such as graduating from school, relocating to a different neighborhood, purchasing a different vehicle, or establishing a stronger credit history. Regularly checking for newly eligible discounts ensures you never pay more than necessary for comprehensive protection. By balancing prudent financial planning with responsible driving habits, you establish a solid foundation for decades of safe, affordable motoring.
Frequently Asked Questions
What is the legal minimum car insurance requirement in the United States?
Auto insurance regulations are determined at the state level rather than federally. Almost all states require minimum amounts of bodily injury liability and property damage liability. Some states also mandate Personal Injury Protection (PIP) or Uninsured Motorist coverage. The sole exceptions are New Hampshire (which does not mandate insurance if drivers demonstrate financial responsibility) and Virginia (which historically allowed an uninsured motorist fee, though mandatory insurance laws have since taken full effect).
How long does a driver remain classified as a “new driver” by insurers?
Insurers generally categorize an operator as an inexperienced or new driver for their first three full years of holding a valid license. During this three-year window, rates remain elevated. Once a driver completes three consecutive years of licensed driving without moving violations or at-fault claims, they typically transition to standard risk pools.
Can a new driver get insured without owning a car?
Yes. If an individual does not own a vehicle but regularly borrows cars from friends or family members, they can purchase a Non-Owner Car Insurance Policy. This policy provides personal liability protection for bodily injury and property damage caused while operating a borrowed or rented car, though it does not provide physical damage coverage for the borrowed vehicle itself.
Does the color of the car affect insurance rates for beginners?
No. Contrary to a persistent urban myth, the color of a vehicle (such as red) has no impact on insurance premiums. Insurers evaluate the Vehicle Identification Number (VIN), which reveals the vehicle’s year, make, model, body style, engine displacement, and safety equipment, but does not record paint color.